Pet Insurance for Chihuahuas: Is It Worth It, What It Costs, What to Check
Pet insurance for a Chihuahua: what it costs, which breed conditions it covers and when it won't, the clauses that matter, and when self-insuring makes more sense.
Few questions come up as often among US members of the club as whether pet insurance for a Chihuahua is worth paying for. The honest answer is: it depends on when you buy it, what the policy actually covers, and how much you could absorb out of pocket on a bad day. This guide doesn’t rank companies, because the right one changes by state, age and budget. It explains what a Chihuahua is likely to need, what a policy will and won’t pay for, and how to read the fine print before you sign.
This article is informational and isn’t financial advice. Quotes and terms change; always read the policy you’re offered.
What is a Chihuahua likely to cost you?
Chihuahuas are long-lived, often 14 to 18 years, which means more years of bills than most breeds. The conditions that drive those bills are predictable:
| Condition | When it tends to show up | Typical US cost range |
|---|---|---|
| Dental disease (cleaning with extractions) | From 3-5 years, recurring | $500 to $1,500+ per cleaning |
| Luxating patella surgery | Often diagnosed before age 1, surgery later | $1,500 to $4,000 per knee |
| Mitral valve disease (echocardiograms, pimobendan) | From 7-10 years, lifelong | $400 to $700 per echo; $40 to $100 a month in medication |
| Collapsed trachea (imaging, medication; stent in severe cases) | Middle age onward | Hundreds for workup; several thousand for a stent |
| Hypoglycemia emergency | Puppies under 3 months | $300 to $1,500 for an ER visit with IV dextrose |
| Seizures (workup, lifelong medication) | Any age | $1,000+ for bloodwork and MRI; ongoing medication |
Those ranges are what club members and published veterinary cost guides report; your city and clinic will land somewhere inside or above them. What matters is the shape: a Chihuahua’s lifetime is a long series of moderate bills, punctuated by one or two big ones. Each condition has its own article in common Chihuahua health problems.
What pet insurance costs
According to the North American Pet Health Insurance Association, the industry’s trade body, accident-and-illness coverage for dogs averaged roughly $62 a month in 2024, and accident-only plans about $16 a month. Only about 5% of US dogs were insured.
A Chihuahua usually quotes below that average while young, because premiums scale with size and age, and this is the smallest breed there is. Expect the premium to rise every year as the dog ages, and to jump noticeably after age 8 or so. That’s the trade-off: insurance is cheapest exactly when the dog needs it least.
Three numbers shape what you’ll actually pay when a claim comes:
- Deductible: what you pay before coverage starts, usually $100 to $1,000 per year. Higher deductible, lower premium.
- Reimbursement rate: the share the insurer pays after the deductible, typically 70%, 80% or 90%.
- Annual limit: the cap on payouts per year, from a few thousand dollars to unlimited.
A $500 deductible with 80% reimbursement means a $3,000 patella surgery costs you $500 plus 20% of the remaining $2,500, or $1,000 out of pocket, and the insurer pays $2,000.
The clauses that matter for a Chihuahua
This is where most disappointment comes from. Read these five before anything else:
- Pre-existing conditions. Anything diagnosed, treated or merely noted by a vet before coverage starts is excluded, usually for life. If the record says “grade 1 luxating patella, monitor,” no knee claim will ever be paid. This is the single biggest reason to insure a Chihuahua as a puppy.
- Waiting periods. Typically 14 days for illness and a few days for accidents, but many insurers apply six months or more to knee and ligament conditions, sometimes waivable with a vet exam. For a breed whose number one orthopedic problem is the kneecap, this clause matters.
- Dental coverage. Routine cleanings are almost never covered without a wellness add-on. Dental disease (extractions, abscesses) is covered by some policies and excluded by others, and some require proof of a cleaning in the past year. For a breed that loses teeth early, this is the clause to read twice.
- Hereditary and congenital conditions. Patellas, hydrocephalus and heart valve disease can be classed as hereditary. Most modern policies cover them; some older or cheaper ones don’t. Check it’s explicit.
- Bilateral conditions. If one knee was treated before enrollment, many policies exclude the other knee too. Ask.
Also worth checking: whether the policy covers prescription medication (pimobendan for years adds up), specialist visits (cardiologists, neurologists), and whether there’s a lifetime cap on top of the annual one.
Accident-only, accident-and-illness, or wellness?
- Accident-only is cheap and covers the fall off the couch, the dog-park bite, the swallowed sock. It covers nothing on the table above except the ER visit for a toxin. For a Chihuahua, it’s the wrong tool.
- Accident-and-illness is the policy that covers patellas, hearts, tracheas and seizures. It’s what “pet insurance” usually means, and the only kind worth comparing for this breed.
- Wellness plans are prepaid routine care (vaccines, cleanings, checkups) bundled for a monthly fee. They’re not insurance; they’re a payment plan. They make sense only if the math works for your clinic’s prices.
When self-insuring makes more sense
Insurance is a bet that something expensive happens before your savings could cover it. If you can put $3,000 to $5,000 in a dedicated account today and leave it alone, you’re covered for the big bills on the table above, and you keep the money if nothing happens. Over a 15-year Chihuahua life, that’s often cheaper than premiums.
Self-insuring loses when the big bill comes early, before the account has grown, or when you know yourself well enough to admit you’d dip into it. It also doesn’t help with the one thing insurance protects you from most: having to choose between a $4,000 surgery and your dog because the money isn’t there this month.
A reasonable middle path many members use: insurance with a high deductible and 80% reimbursement while the dog is young and premiums are low, plus a savings account. Reassess at 8 or 9, when the premium climbs.
How to compare quotes in ten minutes
- Get three quotes for accident-and-illness with the same deductible, reimbursement and annual limit, so you’re comparing like with like.
- Search each policy document for “patella,” “dental,” “hereditary” and “bilateral.” Read those paragraphs only.
- Note the knee waiting period and whether it can be waived.
- Check whether prescription medication is covered.
- Look for a sample claims reimbursement timeline: two weeks is reasonable; two months is not.
- Enroll before the next vet visit, so nothing new lands in the record first.
A club member’s case
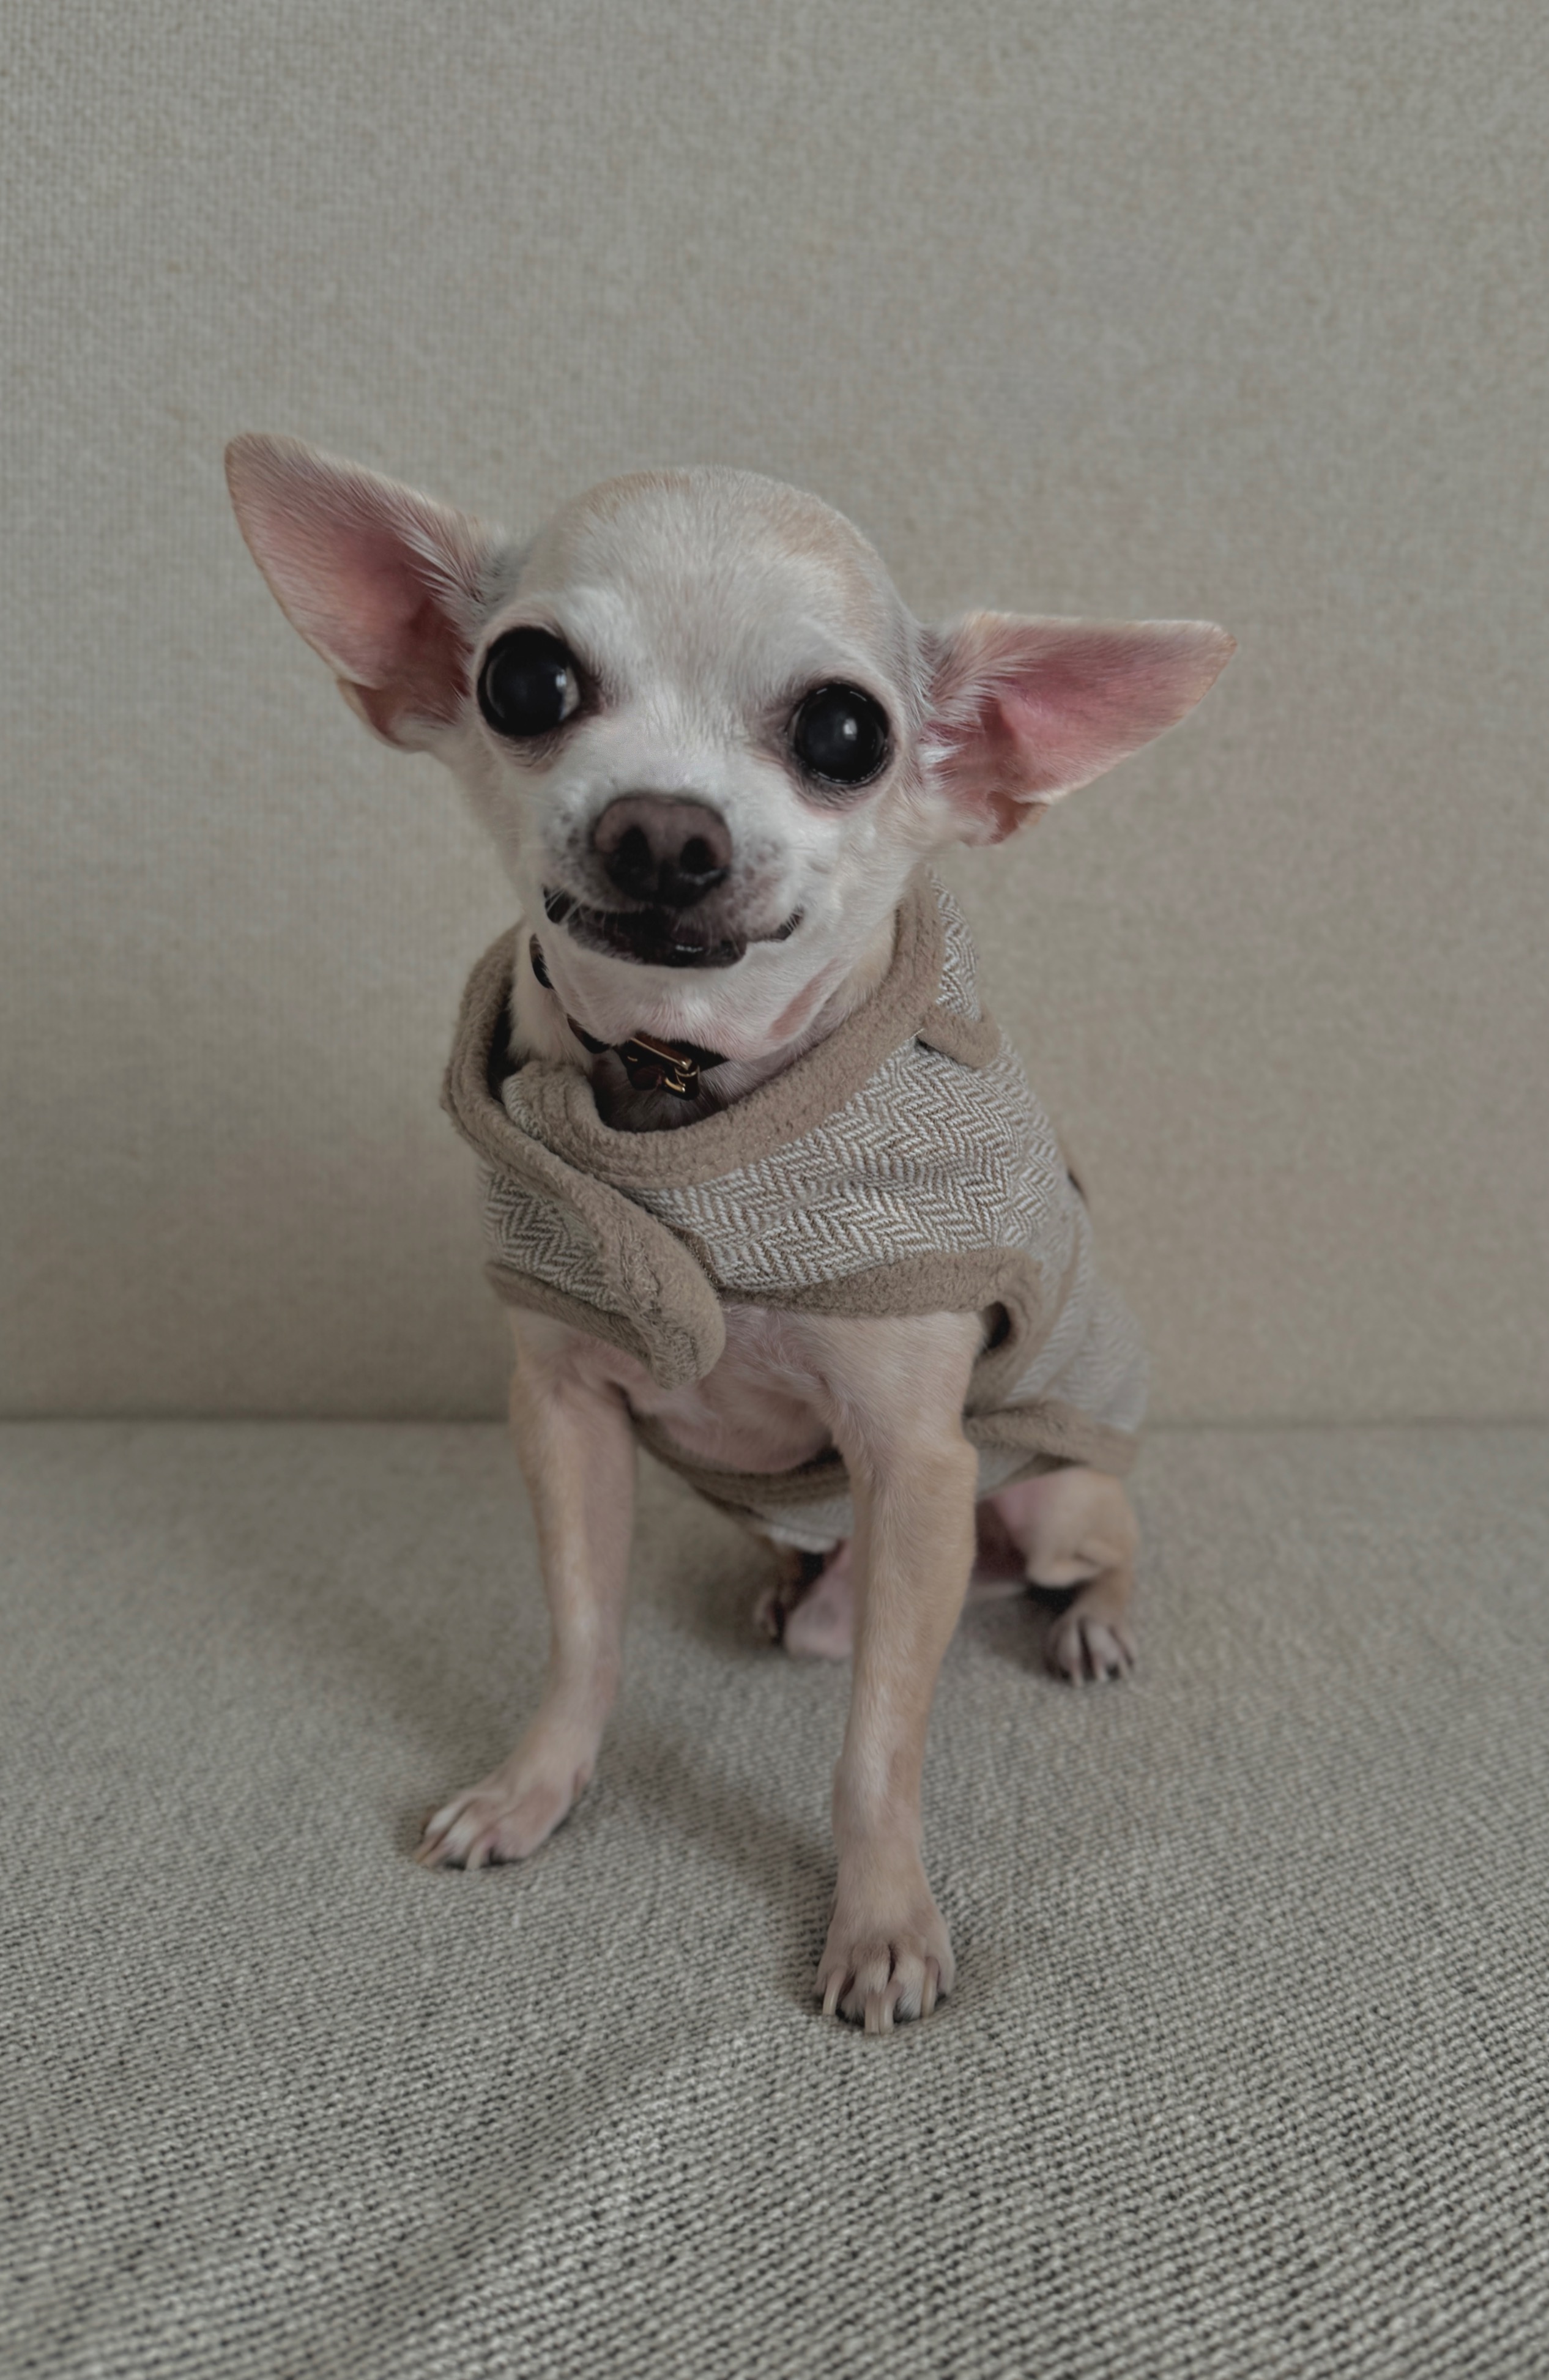
The Chihuahua in the photo is Lucky, from San Luis, Arizona. His family adopted him from a shelter in September 2021, already 12 or 13 years old by the vets’ estimate. A senior shelter dog like Lucky is uninsurable for anything in his record, and premiums at that age are steep anyway. His family did the other thing: regular checkups, a budget set aside, and attention to the signs. That’s the honest version of this article: insurance is a tool, and it works best bought early. Bought late, the tool is a savings account and a good vet.
Romeo is 11 and Lorenzo is 2. If we lived in the US, Lorenzo would be the one to insure today, with a clean record and a premium that reflects a healthy young dog. Romeo, with a murmur already on file, would be the one we save for. For what each stage of life costs and needs, see senior Chihuahua care and how much does a Chihuahua cost.
Frequently asked questions
How much does pet insurance cost for a Chihuahua?
Does pet insurance cover luxating patella in Chihuahuas?
When should I insure a Chihuahua?
Is it better to save money instead of buying pet insurance?
Does pet insurance cover dental cleanings for Chihuahuas?
Written by Belen Salto, who shares her life with Romeo and Lorenzo, two Chihuahuas. · Ver en español